
Weekly Factor Returns

A look at what factors influenced the market last week
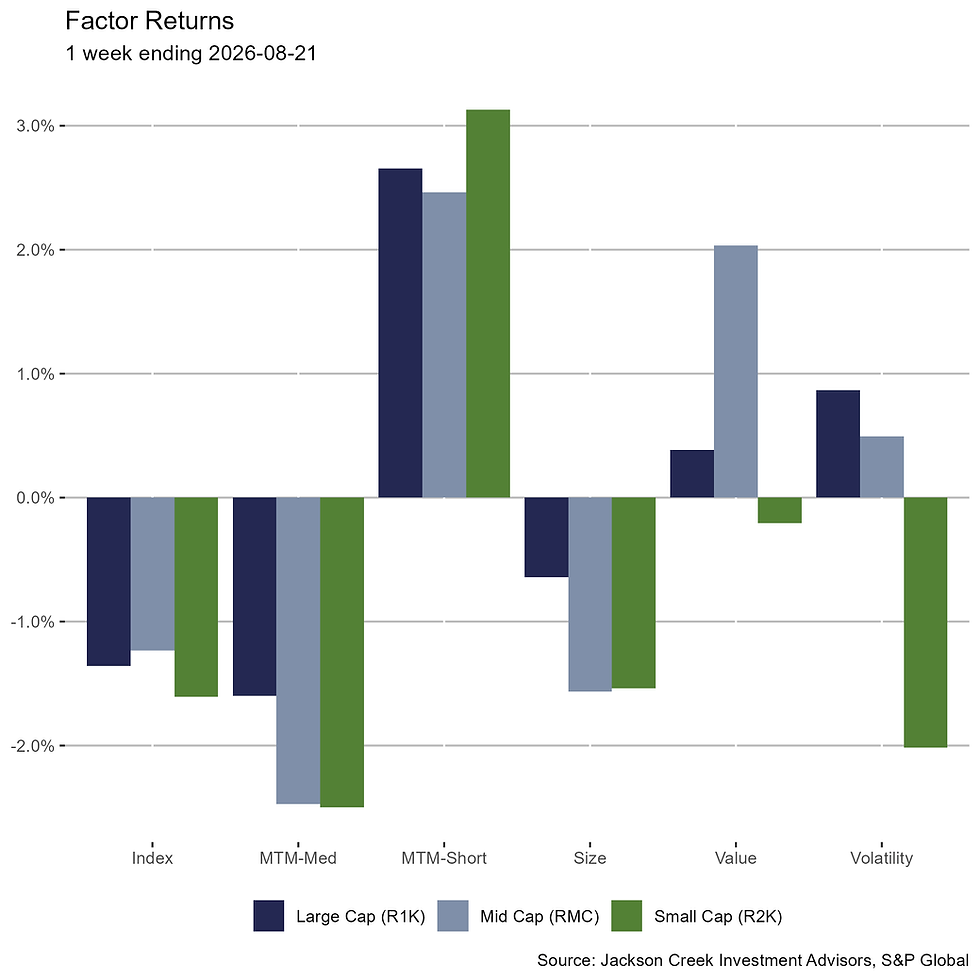
Equities were negative last week with each index falling more than 1.0%. The small cap Russell 2000 declined the most (-1.60%) followed by the large cap Russell 1000 (-1.36%). The Russell MidCap declined 1.23%.
Only three factors had directionally similar returns. One factor had spreads outside normal expectations. Both measures of momentum saw large moves across the capitalization spectrum.
Short-term momentum (STM) rose sharply last week. Stocks that had outperformed the most during the previous four weeks continued to outperform last week. STM rose the most in the small cap universe, where the spread between the most recent winners and most recent losers was +3.13%. STM rose 2.66% in the large cap index and 2.46% among mid caps. Each spread was greater than one standard deviation above its average.
Medium-term momentum (MTM) reversed, particularly among small and mid cap stocks. The stocks that outperformed the most over the previous six months tended to underperform last week. MTM declined by 2.50% in the Russell 2000 and 2.47% in the Russell MidCap. MTM fell by 1.60% in the large cap space.
Size was not a contributing factor to index returns. The smallest companies in each capitalization range outperformed the largest, on average, within each index. The smallest ten percent of companies outperformed the largest ten percent by about 1.5% in the small and mid cap universes. The negative Size spread was smaller in the Russell 1000.
Value and Volatility were directionally similar within each index, which is a departure from their often inversely correlated returns. The small cap spreads were divergent from the mid and large cap spreads. Value was strongly positive among mid cap stocks. The most attractively valued securities outperformed the least attractive by 2.04%, on average. Volatility was negative in the Russell 2000 (-2.01%), while higher Volatility stocks outperformed in the large and mid cap universes.
In this series, we highlight several factors’ returns along with the broad index. These are factors – or stock characteristics – we monitor closely. Factor returns equal the difference in the average return of the highest ranked 10% (decile 1) of stocks minus the lowest ranked 10% (decile 10) within each metric. Returns are based on stocks that pass our screen for liquidity, price, and analyst coverage; therefore, some index constitutes are excluded (except for index return). Ranks are sector neutral and equal weight. Stocks are ranked one week before the return period date, with returns calculated for the following week.
Read factor explanations here.
The Russell 1000 Index is a U.S. stock market index that tracks the highest-ranking 1,000 stocks in the Russell 3000 Index, which represent about 93% of the total market capitalization of that index.
The Russell Midcap Index is a stock market index that measures performance of the 800 smallest companies in the Russell 1000 Index.
The Russell 2500 Index measures the performance of the 2,500 smallest companies in the Russell 3000 Index, with a weighted average market capitalization of approximately $4.3 billion, median capitalization of $1.2 billion and market capitalization of the largest company of $18.7 billion.
The Russell 2000 Index is a small-cap U.S. stock market index that makes up the smallest 2,000 stocks in the Russell Index. It was started by the Frank Russell Company in 1984. The index is maintained by FTSE Russell, a subsidiary of the London Stock Exchange Group.
Index performance is presented as a benchmark for reference only and does not imply any portfolio will achieve similar returns, volatility or any characteristics similar to any actual portfolio. The composition of a benchmark index may not reflect the manner in which any is constructed in relation to expected or achieved returns, investment holdings, sectors, correlations, concentrations or tracking error targets, all of which are subject to change over time. You cannot invest directly in an index. Index performance does not reflect the deduction of any investment management fees, transaction costs, or expenses, and the performance of any investment product may differ from the index.


Comments